Tax planning plays a key role in wealth creation.
Yet, many miss out on what is essentially “free money” by viewing tax planning as a secondary or tertiary concern in their financial plan.
In reality, tax-efficient saving and investing could help you:
- Retire sooner
- Achieve your goals quicker
- Enjoy a more luxurious lifestyle in retirement.
Your tax planning strategy might hinge on the effective use of two tax wrappers: pensions and ISAs.
Tax wrappers shelter your wealth from different types of tax
Tax wrappers are secure financial products or legal rules that shelter your wealth from different taxes. They generally function in two primary ways:
- Wealth inside a tax wrapper is shielded from various taxes.
- Storing your wealth in a tax wrapper allows you to benefit from tax relief.
Tax wrappers enhance the efficiency of your wealth, and while the real-terms value varies, small amounts can add up over time. Additionally, you can reinvest tax-efficient funds in certain circumstances, allowing your wealth to benefit more from compound growth.
Tax wrapper one: Pensions
Pensions are effective wrappers for building long-term wealth.
In fact, you may be receiving pension tax relief without knowing it.
When you make pension contributions, tax relief is automatically applied at a rate of 20%, in line with the basic rate of Income Tax (provided you pay the basic rate). For every £80 of post-tax net income you contribute, the government will top up your pension with an additional £20.
The higher your tax band, the more relief you can claim.
If you are a higher- or additional-rate taxpayer, you can claim relief at your respective rates (40% or 45%) through Self Assessment.
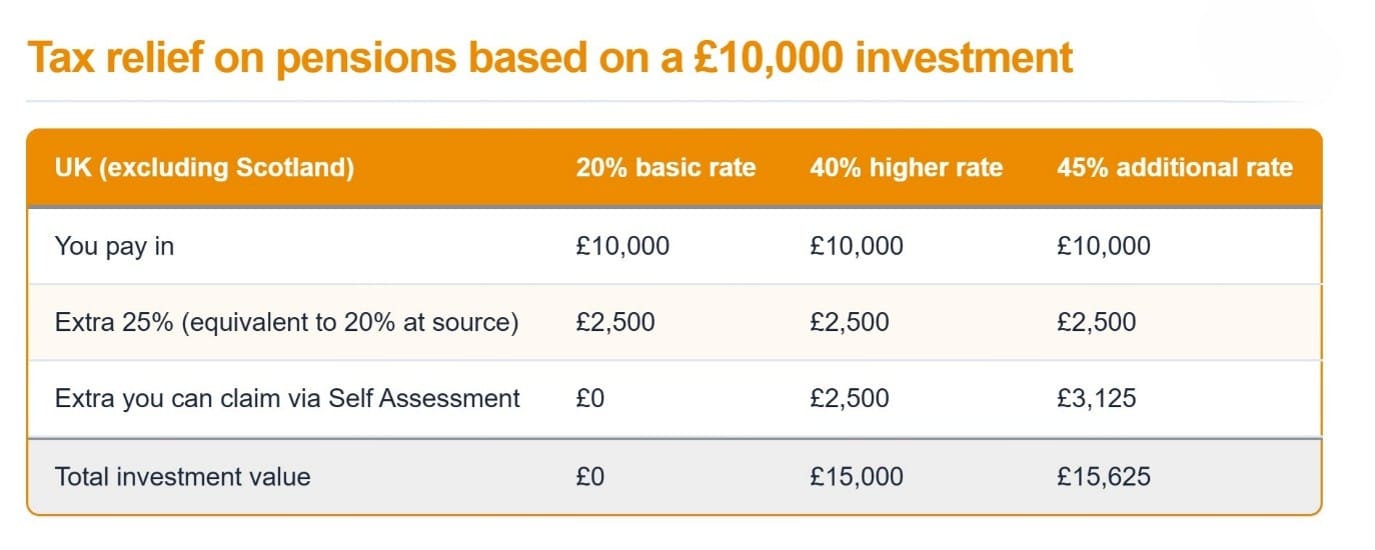
Source: Legal and General
The maximum amount of pension tax relief you can claim on your contributions is capped by the Annual Allowance, which is £60,000 as of the 2026/27 tax year. You can also claim tax relief on pension contributions up to 100% of your annual earnings.
However, your Annual Allowance may be lower if you are a high earner or have flexibly accessed your pension.
Tax wrapper two: ISAs
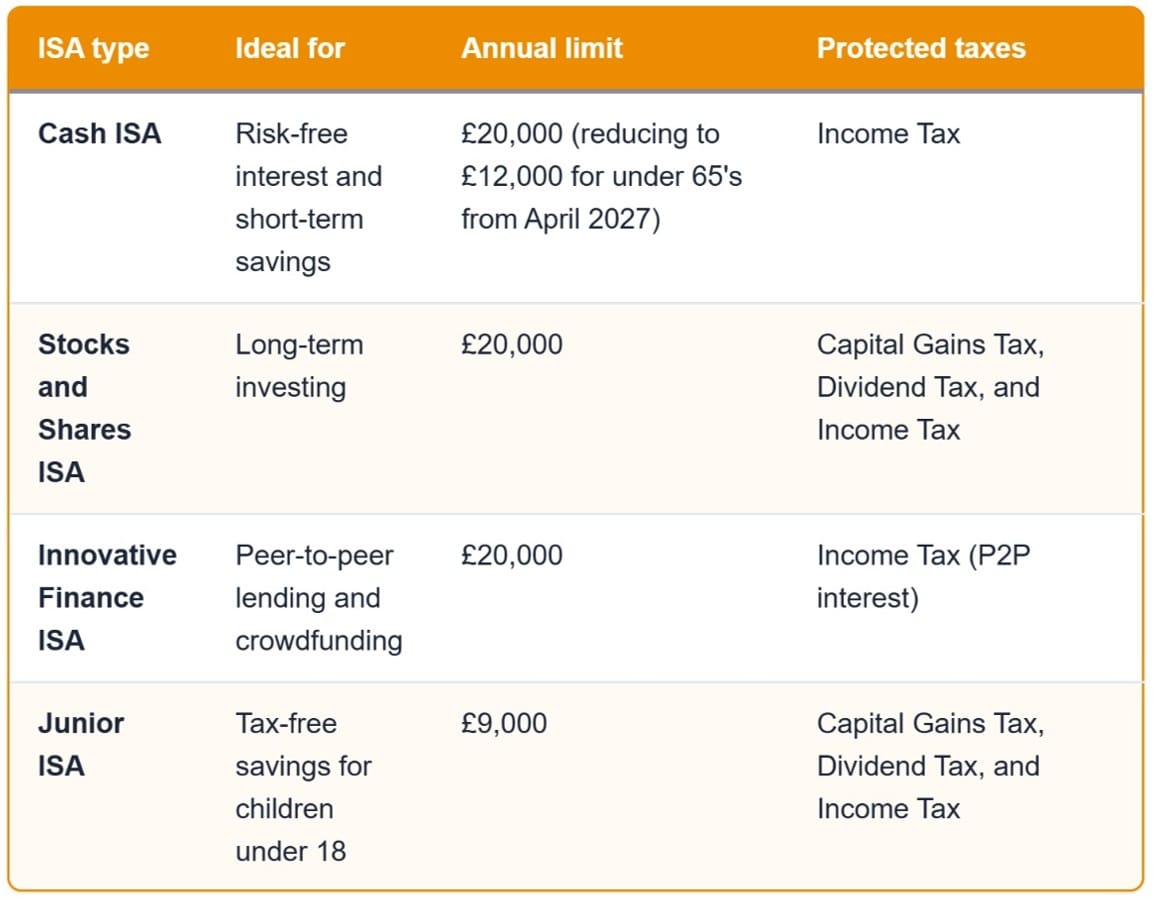
Rather than providing tax relief on contributions, ISAs allow tax-efficient gains by protecting interest and investment growth from Income Tax, Capital Gains Tax, and Dividend Tax.
This tax efficiency applies up to the annual subscription limit, which is currently £20,000 in the 2026/27 tax year, and is split across your ISA holdings.
Please note: if you are under 65, the subscription limit is reducing to £12,000 for Cash ISAs from April 2027. This change does not impact other ISA limits. At the same time, the government is introducing a flat 22% tax on interest earned from uninvested cash held inside non-Cash ISAs.
There are various types of ISAs, each with its own benefits, limits, and tax protections.
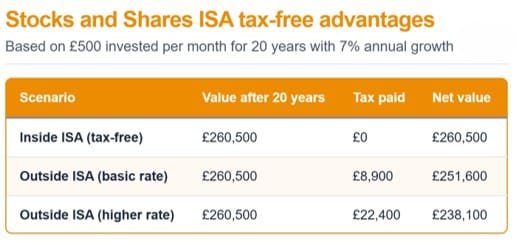
Below is an example of how much basic- and higher-rate taxpayers could save over a period of 20 years when investing in a Stocks and Shares ISA (with an assumed annual growth rate of 7%), based on Smart Investor UK data.
Use these wrappers effectively to harness their unique tax benefits
Pensions and ISAs are core pillars in tax planning. How you use them impacts how much wealth you can build.
Tax-efficient pension savings are locked away until you reach the normal minimum pension age
Pensions are most effective for supporting your later-life goals.
This is because your contributions are locked away until you reach the normal minimum pension age (NMPA). The NMPA is currently 55, but will increase to 57 in April 2028.
Additionally, pension wealth is invested, meaning it benefits from compound growth. On average, FTAdviser reports that pension wealth held in a defined contribution pension triples over the course of your life, thanks to investment growth, tax efficiency benefits, and employer contributions. This makes it ideal for supporting your long-term retirement goals.
You must carefully plan how much wealth you can afford to contribute to your pension regularly so that your short-term needs are protected.
ISAs provide tax-efficient wealth for short- and medium-term goals
Stocks and Shares ISAs can also benefit from investment growth, and ISAs generally have fewer access restrictions, making them ideal for supporting your short- and medium-term goals.
ISAs can also contribute towards long-term goals. However, the level of tax benefits provided by pensions means you could generate a higher future income by increasing contributions to your pension rather than to your ISAs.
Get started with your Milsted Langdon financial planner
We can help you build your tax wrapper strategy from scratch, tailored to your unique circumstances and goals.
Please get in touch or email us at advice@mlifa.co.uk for more information today.
Please note
This article is for general information only and does not constitute advice. The information is aimed at individuals only.
All information is correct at the time of writing and is subject to change in the future.
Please do not act based on anything you might read in this article. All contents are based on our understanding of HMRC legislation, which is subject to change.
The Financial Conduct Authority does not regulate tax planning.
A pension is a long-term investment not normally accessible until 55 (57 from April 2028). The fund value may fluctuate and can go down, which would have an impact on the level of pension benefits available.
The tax implications of pension withdrawals will be based on your individual circumstances. Thresholds, percentage rates, and tax legislation may change in subsequent Finance Acts.
The value of your investments (and any income from them) can go down as well as up and you may not get back the full amount you invested. Past performance is not a reliable indicator of future performance.
Investments should be considered over the longer term and should fit in with your overall attitude to risk and financial circumstances.